Premia Insights
featured insights & webinar
The virous outbreak becomes one of the largest threats to the global economy and financial markets in decades. Will China, the one which has been suffered from the pandemic first, be able to bounce back first and lead the recovery worldwide like the Global Financial Crisis back in 2008? The latest call in new infrastructure investment maybe the key.
Mar 19, 2020
COVID-19 spread accelerating in the US, even as the number of new infections in China eases Impact will be significant on the largely consumer-driven US economy Markets are either in or on the brink of bear territory, and this is an angry bear Recession likely already in progress in Japan; possible recession in Europe; near zero GDP growth likely in the US by 2Q20 Corporate credit protection costs have started rising – more trouble ahead Seek safety in cash and US Treasury-related instruments
Mar 09, 2020
The coronavirus situation in China seems to have improved a lot, and now many are worried about what will happen as the factories get back on their feet. How's the progress so far?
Mar 09, 2020
Relief rally unlikely to last Beyond COVID-19, economies could flatline or enter recession Corporate earnings could stop growing at a time of heightened valuations There is a tail risk of credit defaults on liquidity and cashflow squeeze
Mar 02, 2020
As we expected, markets did bounce on policy stimulus hopes. While rate cuts and liquidity injections will make markets feel better for a while at least, what is it likely to do for the economy?
Mar 02, 2020
As Asia deal with the challenges from the outbreak of coronavirus, one remarkable phenomenon is the massive behavioural change from offline to online across the billions population. In this webinar, we will share with you the key structural megatrends in Asia, how technology-enabled development is creating a more empowering, inclusive society, and how such blitzscaling opportunities can be captured in the form of our Asia Innovative Technology strategy.
Mar 02, 2020
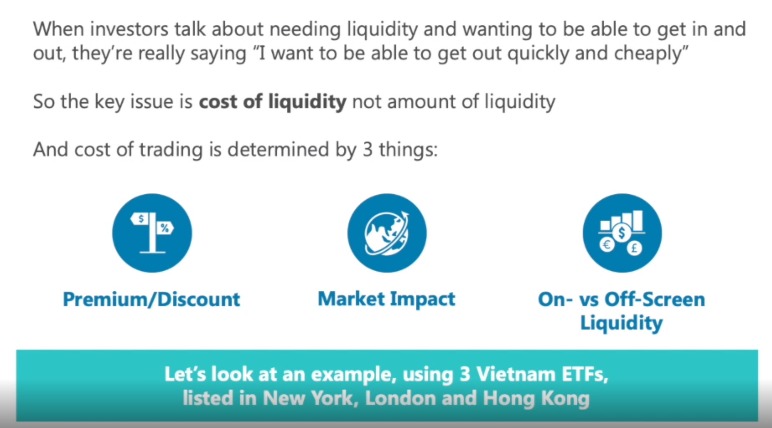
We often hear from clients that they love certain Asia strategies, but have to resort to ETFs traded in the US or Europe due to ETF liquidity considerations. But what they really mean, is not the ETF liquidity itself, but rather the cost of liquidity that investors are worried about. Liquidity is a proxy for cost – the less liquid something is the more it’ll cost to get in and out, particularly during crises or market dislocations where whatever liquidity exists can go to 0. While a lot of investors trade Asian risk in the US and Europe, thinking that it is cheaper and more efficient where the ETF liquidity is, that is actually not the full picture. In this webinar, we would like to share with you a series of comparisons for a niche market, Vietnam, across ETFs listed in NY, London and HK.
Mar 01, 2020
The sharp pullback in developed markets could see 10% knocked off the S&P 500 The correction was due to a more complex mix of factors than just COVID-19 A rebound could emerge on monetary stimulus hopes But deeper problems of overvaluation and negligible earnings growth will remain to trouble markets later in the year
Feb 24, 2020
Recent market rallies, despite COVID-19, are neither “ill informed” nor “complacent” Markets are looking past the viral outbreak Stocks will likely return to being driven by whatever the trends were before the outbreak Developed markets are at the tail end of bull moves – they could edge a bit higher but the risks are on the downside, and that's got nothing to do with COVID-19 either Chinese equities could ironically outperform developed market stocks this year
Feb 23, 2020
On account of an atypical, tech-enabled start of the Year of the Rat, what are people doing during this very unusual Chinese New Year holiday period? While the roads are empty and quiet, we see extremely busy traffic online from social gathering and entertainment to post-holiday work arrangements all thanks to technology - which enabled an unconventional time of family reunion, and possibly fast-tracked development of enterprise digital transformation in the way.
Feb 02, 2020
BY TOPICS
Chart Of the Week
Michael Ng
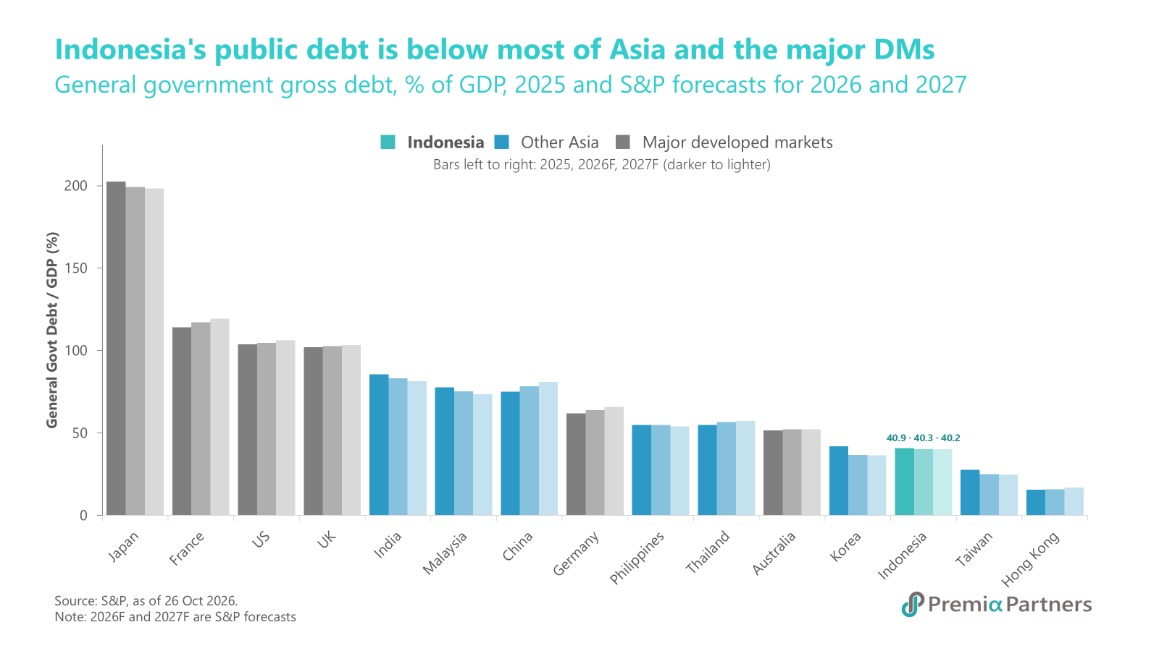
Indonesia's fiscal position is stronger than the recent sell-off implies. S&P puts general government debt at 40.9% of GDP in 2025, the third lowest of the 15 markets in the chart, and expects it to hold broadly steady at 40.3% in 2026 and 40.2% in 2027. That compares with a simple Asian average of 52.7% easing to 51.7%, and a major developed-market average of 106.0% rising to 107.6%. Japan, India, Malaysia and China all carry heavier debt loads.What rattled markets was an equity-market issue, not a fiscal one. On 15 October, MSCI proposed moving Indonesia from “Emerging Market“ to “Standalone Market“ status, citing opaque shareholding structures and suspected coordinated trading. Jakarta shares fell 11.6% in a single session, the steepest one-day drop since 1998. Indonesia government international bonds and sukuk, by contrast, barely flinched: five-year CDS widened from roughly 84–88bp in late September to around 100bp by 22 October, with part of that move predating MSCI's announcement and tracking higher US Treasury yields.Nothing has yet changed in Indonesia's index status. MSCI will consult until April 2027 and announce a final decision by 30 June 2027, leaving time for reform. Authorities have already moved, mandating a 15% minimum free float, requiring disclosure of 1% shareholdings and removing highly concentrated stocks from the JCI. Enforcement will decide the outcome, but if these measures stick, the episode could leave Indonesia with a more transparent and investable market than before.The Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF (3411 / 9411 HK) holds Indonesia as one exposure among many. The ETF spans 124 issuers across Asia ex-Japan, with Indonesia at roughly 15%: about 10% across Indonesian government bonds and sukuk, and 5% across quasi-sovereign and corporate names including Bank Mandiri, Freeport Indonesia, Indofood, Indonesia Asahan Aluminium, Minejesa Power, Pertamina and PT Perusahaan Listrik Negara - high-quality investment-grade issuers.
Oct 28, 2026