Premia Insights
featured insights & webinar
3 of our ETFs recently went through their annual index rebalances. While investors focus mainly on fees and liquidity, the rebalancing and index methodology of ETFs are equally, if not more, important to the investor experience and returns. To that end, we’d like to highlight June’s rebalances and explain what investors can expect going forward.
Jul 12, 2019
Vietnam is increasingly spoken about as one of the biggest beneficiaries of the trade war and as a market to watch going forward. However, the tools to access Vietnam remain limited. On July 18 (subject to final approvals) we will list the MSCI Vietnam strategy to make it easier for investors to access this dynamic and fast growing market.
Jul 03, 2019
The highly anticipated G20 Summit seemed to have concluded in a nice conciliatory note as the world powers converged in Osaka this past weekend. Or did it? While it seemed to have eliminated the “total risk-off” worst case scenario, and perhaps rebuilt confidence for China equities especially the new economy sectors, beyond the rhetoric, what we have is not really a pause in the trade war. The war continues as evident in the tariffs. A more accurate description is that both sides have agreed not to escalate the trade war while talks resume.
Jul 01, 2019
Whatever happens over coming weeks and even months in the US-China trade war, Donald Trump has irreparably broken the global trade architecture. And with it, he has also forced a realignment of the global supply chain that will likely see ASEAN emerge as a new manufacturing centre.
Jun 26, 2019
As we head toward the G20 meeting in Osaka, we take a moment to review the latest status of the trade war between the two largest economies today. Is it about containment or tariffs? How does the current situation compare to Japan in the ‘80s? Do either China or the US actually want to make a deal? What are the possible paths going forward?
Jun 11, 2019
As we approach the end of 1H19, it is clear that the market now finds itself in a tug of war between the Fed Put and the potential for recession. We explore this dynamic, discuss Q1 vs future growth across the 4 major economies (US, Europe, Japan and China) and remind investors to stay defensive going forward by tilting toward value and quality where possible.
Jun 11, 2019
The Global Mobile Communication Systems Association estimates that by the end of this year, 5G services will be available in 29 markets around the world, with 10 million connections. What is 5G and where do we see potential investment opportunities from this significant technology upgrade in Asia?
Jun 05, 2019
As the issuer of world’s first two fundamental multifactor China A-shares ETFs, we look closely into the factors. The China A shares market went on a roller coaster ride since late 2018, and how about the factors – are they on the same ride or rotating around a Ferris wheel? In this piece, we re-cap the research on China A fundamental factors and share the recent observations on factor performances.
Jun 02, 2019
Investors looking for China’s NASDAQ seem to have settled on ChiNext as the default index to follow. BUT what if there is an even better option in the market, offering a more appropriate China new economy exposure with better performance, higher quality, lower volatility and discounted valuations?! It may sound too good to be true, but it is exactly what the Premia China New Economy ETF (3173.HK) has achieved so far.
May 19, 2019
Most investors assume that the more liquid the ETF, the easier and cheaper it is to trade. This is true in markets like the US, where on-screen liquidity is prevalent, but Asia markets are not as straightforward. China A ETFs with on-screen liquidity are easy to trade, but easier does not always mean cheaper to trade. There is market risk in trading on-screen and though it is easier, it can actually be more expensive than trading via the underling liquidity of China A stocks inside the ETF.
May 15, 2019
BY TOPICS
Chart Of the Week
Michael Ng
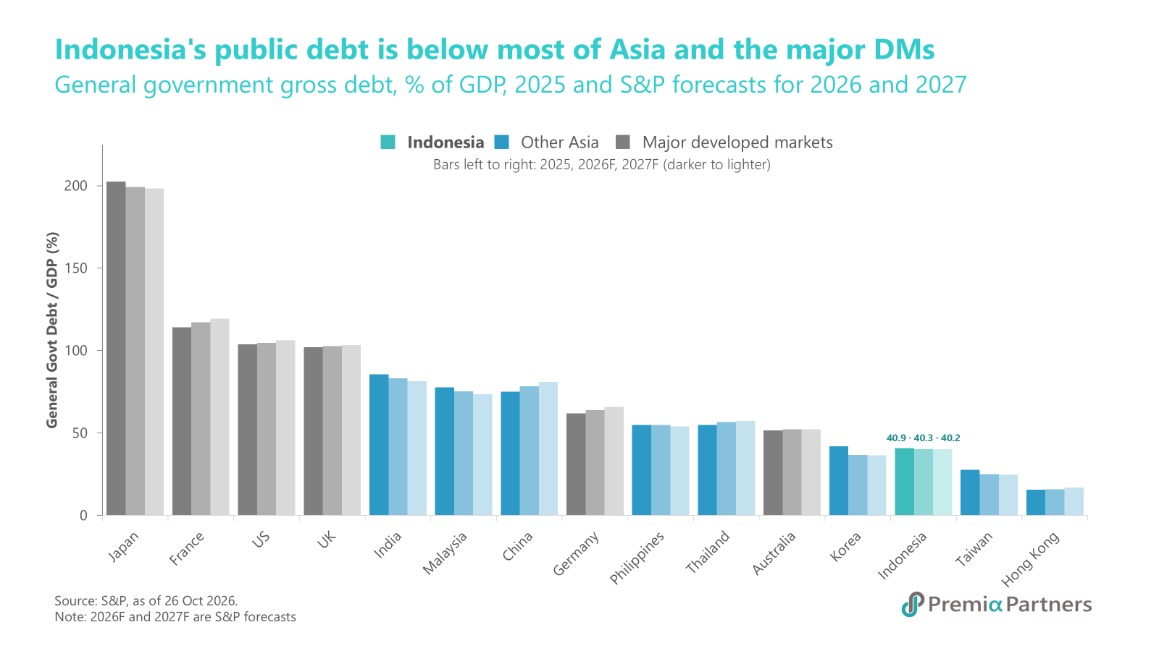
Indonesia's fiscal position is stronger than the recent sell-off implies. S&P puts general government debt at 40.9% of GDP in 2025, the third lowest of the 15 markets in the chart, and expects it to hold broadly steady at 40.3% in 2026 and 40.2% in 2027. That compares with a simple Asian average of 52.7% easing to 51.7%, and a major developed-market average of 106.0% rising to 107.6%. Japan, India, Malaysia and China all carry heavier debt loads.What rattled markets was an equity-market issue, not a fiscal one. On 15 October, MSCI proposed moving Indonesia from “Emerging Market“ to “Standalone Market“ status, citing opaque shareholding structures and suspected coordinated trading. Jakarta shares fell 11.6% in a single session, the steepest one-day drop since 1998. Indonesia government international bonds and sukuk, by contrast, barely flinched: five-year CDS widened from roughly 84–88bp in late September to around 100bp by 22 October, with part of that move predating MSCI's announcement and tracking higher US Treasury yields.Nothing has yet changed in Indonesia's index status. MSCI will consult until April 2027 and announce a final decision by 30 June 2027, leaving time for reform. Authorities have already moved, mandating a 15% minimum free float, requiring disclosure of 1% shareholdings and removing highly concentrated stocks from the JCI. Enforcement will decide the outcome, but if these measures stick, the episode could leave Indonesia with a more transparent and investable market than before.The Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF (3411 / 9411 HK) holds Indonesia as one exposure among many. The ETF spans 124 issuers across Asia ex-Japan, with Indonesia at roughly 15%: about 10% across Indonesian government bonds and sukuk, and 5% across quasi-sovereign and corporate names including Bank Mandiri, Freeport Indonesia, Indofood, Indonesia Asahan Aluminium, Minejesa Power, Pertamina and PT Perusahaan Listrik Negara - high-quality investment-grade issuers.
Oct 28, 2026