주요 인사이트 & 웨비나
As we approach the end of 1H19, it is clear that the market now finds itself in a tug of war between the Fed Put and the potential for recession. We explore this dynamic, discuss Q1 vs future growth across the 4 major economies (US, Europe, Japan and China) and remind investors to stay defensive going forward by tilting toward value and quality where possible.
Jun 12, 2019
The Global Mobile Communication Systems Association estimates that by the end of this year, 5G services will be available in 29 markets around the world, with 10 million connections. What is 5G and where do we see potential investment opportunities from this significant technology upgrade in Asia?
Jun 06, 2019
As the issuer of world’s first two fundamental multifactor China A-shares ETFs, we look closely into the factors. The China A shares market went on a roller coaster ride since late 2018, and how about the factors – are they on the same ride or rotating around a Ferris wheel? In this piece, we re-cap the research on China A fundamental factors and share the recent observations on factor performances.
Jun 03, 2019
Investors looking for China’s NASDAQ seem to have settled on ChiNext as the default index to follow. BUT what if there is an even better option in the market, offering a more appropriate China new economy exposure with better performance, higher quality, lower volatility and discounted valuations?! It may sound too good to be true, but it is exactly what the Premia China New Economy ETF (3173.HK) has achieved so far.
May 20, 2019
Most investors assume that the more liquid the ETF, the easier and cheaper it is to trade. This is true in markets like the US, where on-screen liquidity is prevalent, but Asia markets are not as straightforward. China A ETFs with on-screen liquidity are easy to trade, but easier does not always mean cheaper to trade. There is market risk in trading on-screen and though it is easier, it can actually be more expensive than trading via the underling liquidity of China A stocks inside the ETF.
May 16, 2019
ASEAN equity markets have underperformed so far this year. Is it the start of a new trend, or simply a blip given the strong reversal in China? Say Boon Lim shares his views on why ASEAN is likely to outperform going forward.
May 06, 2019
Nasdaq has made new highs and investors are understandably excited. Similarly, here in Asia we have seen innovative technology companies outperform YTD but with much less fanfare. David Lai explores the major megatrends in Asia and why you need to invest in tech leaders across this region.
May 03, 2019
Looking past stellar Q1 returns, we discuss positioning going forward and the need to navigate the conflicting signals offered by equity and bond markets today
Apr 10, 2019
With the CSI300 up ~25% YTD, many clients are worried that the market has fully priced in the MSCI inclusion. We review 5 flawed assumptions and explain why the rally is just the start of a long-term trend.
Mar 26, 2019
As China markets reacted to expansionary policy news, familiar criticism of China’s debt and leverage concerns has begun to emerge from global investors. Separating myths from reality, our advisor Say Boon Lim shares his thoughts on the 5 biggest myths about China’s economy.
Mar 13, 2019
토픽별
주간 차트
Michael Ng
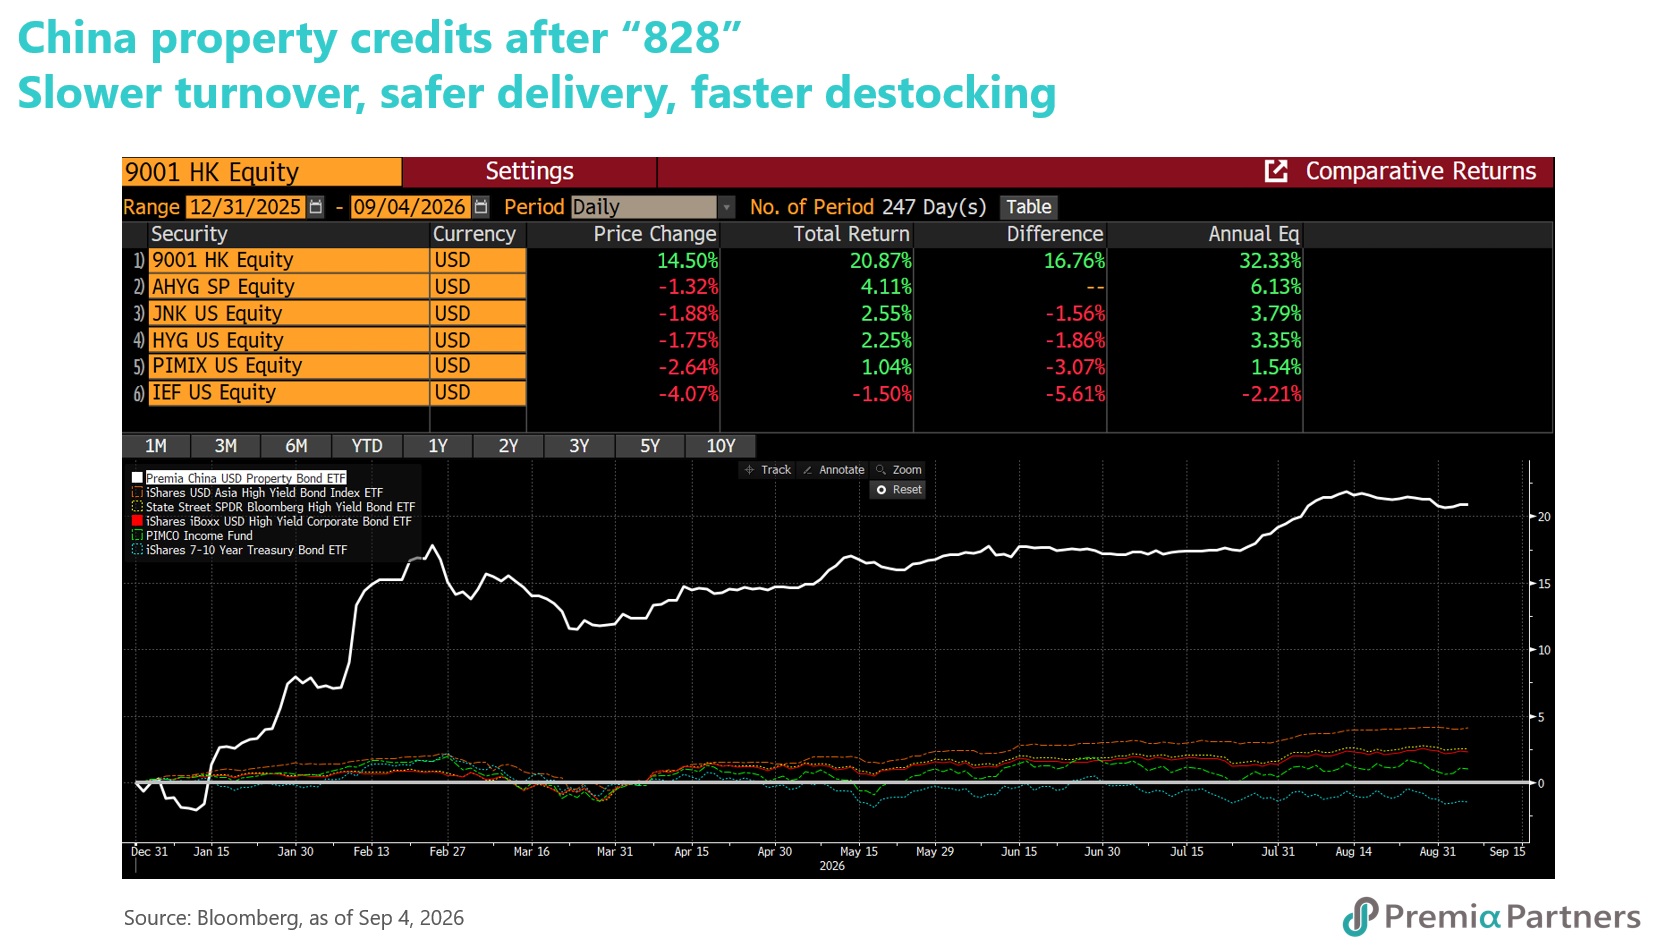
China property USD bonds have extended gains through the third quarter, with the Premia China USD Property Bond ETF (3001/9001 HK) up more than 20% year to date. On 28 August, Beijing announced the most significant overhaul of China's housing sales and financing framework in three decades. It works through four channels:Sales milestones reset. MOHURD, MNR and NFRA now require a building to be structurally topped out before presales can begin, with 100% of purchase funds — down payments and mortgage proceeds — held in supervised escrow until completion and delivery.Lead-bank oversight. Designated banks supervise project financing, escrow and construction progress end to end, and a homebuyer's mortgage is now issued only after the project is completed.Longer mortgage tenors. The PBOC lifted the maximum personal mortgage tenor from 30 to 40 years.Wider capital-market access. The CSRC broadened refinancing and M&A channels, alongside expanded REIT, CMBS and ABS support for income-producing assets.While the near-term read is negative for developers - replacing presale proceeds with borrowing implies higher leverage and more secured debt, which can subordinate existing senior claims - that argues for selection rather than avoidance. The Premia China USD Property Bond ETF (3001 / 9001 HK) holds secured and senior unsecured paper only, and excludes subordinated debt and LGFVs, favouring issuers with recurring rental income and the securitisation access the CSRC has just widened. Over the medium to long term, the reform should reduce the risk of another property-sector shock. Delivery risk moves off household prepayments and into bank-supervised project finance, lowering the odds of a repeat of the unfinished-project stress that drove the last default wave, while tighter new-home supply supports the clearing of existing inventory. Meanwhile, banks are being capitalised to carry that risk: Beijing announced a further RMB360bn (US$54bn) injection into eight state financial institutions on 6 September, of which RMB290bn (US$43.2bn) went to lenders. Brokers expect developer equities to stay soft unless policy surprises or sales data improve. Bonds answer a different question: not whether growth returns, but whether issuers keep paying. The ETF yields around 12.9% (as of Sep 8, 2026), well above the broader Asia high yield market - the extra income investors are paid for the risk that some issuers still restructure or default while the transition plays out.
Sep 10, 2026