Premia 观点洞察
精选观点 & Webinar
随着COVID疫情走向复甦,中美摩擦等地域风险逐渐晴朗,2021投资者可以如何佈局? 我们的联合首席投资官赖子健先生与我们团队的郭子豪先生为大家分享对亚洲高成长地区及高成长行业的展望,「我们可以如何通过Premia的投资策略来捕捉这些大趋势下的盈利机遇,并讨论了对近期市场环境相关热门话题的看法。
Jan 03, 2021
Outperformer from first news of successful vaccines. Emerging ASEAN has been one of the best performers among major global equity indices since the start of November. And that was likely due to the region’s high economic leverage to normalisation after the distribution of COVID-19 vaccines and its high trend GDP growth rates relative to other Emerging Market economies.
Dec 23, 2020
To summarize the year of 2020, the opening lines from Charles Dicken’s A Tale of twin cities sounds like an accurate description. It was certainly the best of times and the worst of times. Global equities have been doing reasonably well with developed market up by 12.0% and emerging market up by 11.7%. Fixed income managed to gain by 7.4% whilst gold price was up by 19.1%. On the other hand, real economy has been suffering from the pandemic with almost all major economies getting into recession. International Monetary Fund sees the world would contract by 4.4% in total output, the worst crisis since the 1930s Great Depression with -5.8% among advanced economies and -3.3% on developing countries.
Dec 01, 2020
From a total portfolio perspective, global asset owners and allocators are increasing wary about the overall portfolio sensitivity to interest rate changes and ultimately risk diversification. The concept of “equity duration” was raised long ago and has been subject to debate for decades. While some absolute calculations fail to work in today’s markets, we believe the economic and financial intuition beneath still hold. In this working paper, we took a renewed approach to analyze the relationships from a relative perspective and with an overarching objective of total portfolio risks in mind.
Nov 25, 2020
As business activities in China mostly resume to a normal level, we also observed some mean-reversion in factor returns, and interesting rotation in sector returns. Still, China A shares continue to outperform the US and global equity markets. With “high-quality” growth emphasized by the 14th Five-Year Plan and “Dual Circulation”, we believe “Quality Growth” will continue to be the main tone of China A equities.
Nov 10, 2020
So, it is official: Exit Donald Trump, enter President Joe Biden. And when the cheering and crying is done, we are likely to see that the election meant more emotionally to Americans than it does economically for the nation, or financially for the markets. The big economic and market trends are unlikely to be changed by the election.
Nov 08, 2020
The term "dual circulation” is one of the hot searches in China and receives great attention after President Xi first expressed this idea at a top official meeting held earlier this year. He then elaborated further that China’s economic model will be involving an internal circulation developing a substantial domestic market, and an external circulation deepening the international trade. The latest meeting of Communist Party’s Central Committee reinforced this policy will be the core component of the 14th five-year plan for the development between 2021 and 2025.
Nov 03, 2020
Premia 图说
吴伟锋
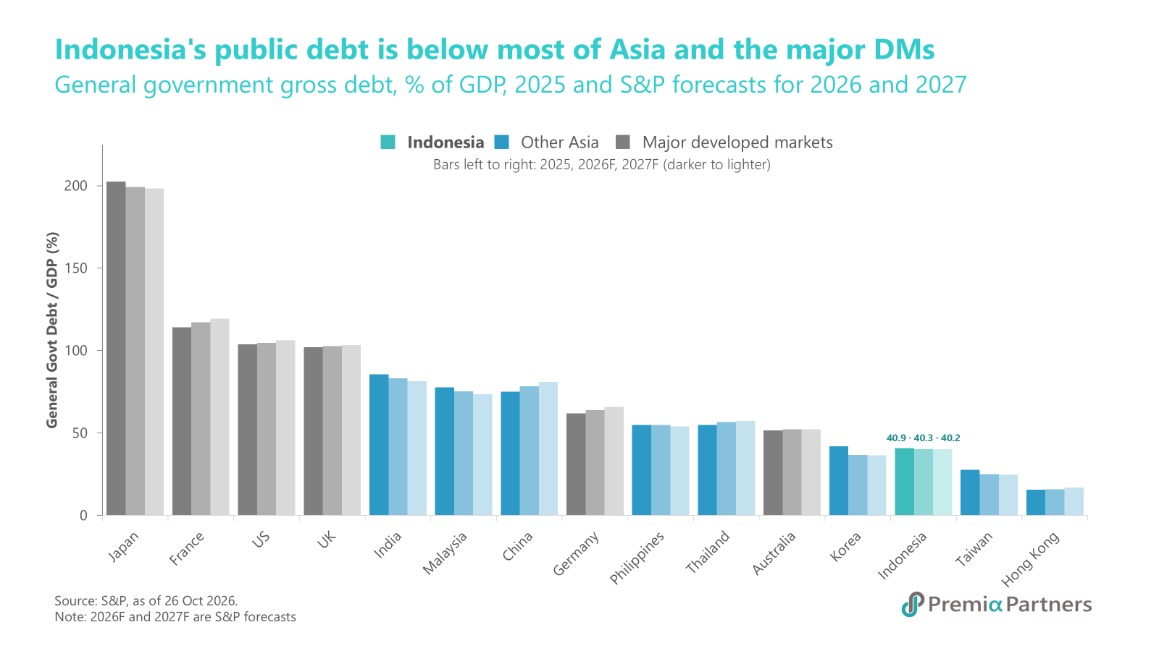
Indonesia's fiscal position is stronger than the recent sell-off implies. S&P puts general government debt at 40.9% of GDP in 2025, the third lowest of the 15 markets in the chart, and expects it to hold broadly steady at 40.3% in 2026 and 40.2% in 2027. That compares with a simple Asian average of 52.7% easing to 51.7%, and a major developed-market average of 106.0% rising to 107.6%. Japan, India, Malaysia and China all carry heavier debt loads.What rattled markets was an equity-market issue, not a fiscal one. On 15 October, MSCI proposed moving Indonesia from “Emerging Market“ to “Standalone Market“ status, citing opaque shareholding structures and suspected coordinated trading. Jakarta shares fell 11.6% in a single session, the steepest one-day drop since 1998. Indonesia government international bonds and sukuk, by contrast, barely flinched: five-year CDS widened from roughly 84–88bp in late September to around 100bp by 22 October, with part of that move predating MSCI's announcement and tracking higher US Treasury yields.Nothing has yet changed in Indonesia's index status. MSCI will consult until April 2027 and announce a final decision by 30 June 2027, leaving time for reform. Authorities have already moved, mandating a 15% minimum free float, requiring disclosure of 1% shareholdings and removing highly concentrated stocks from the JCI. Enforcement will decide the outcome, but if these measures stick, the episode could leave Indonesia with a more transparent and investable market than before.The Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF (3411 / 9411 HK) holds Indonesia as one exposure among many. The ETF spans 124 issuers across Asia ex-Japan, with Indonesia at roughly 15%: about 10% across Indonesian government bonds and sukuk, and 5% across quasi-sovereign and corporate names including Bank Mandiri, Freeport Indonesia, Indofood, Indonesia Asahan Aluminium, Minejesa Power, Pertamina and PT Perusahaan Listrik Negara - high-quality investment-grade issuers.
Oct 28, 2026