Premia 觀點洞察
精選觀點 & Webinar
China’s financial markets stand on the cusp of resilience and opportunity, buoyed by proactive government interventions and structural reforms. Beijing’s commitment to fostering innovation in artificial intelligence, semiconductors, and renewable energy highlights its strategic pivot towards self-reliance. Meanwhile, reforms aimed at enhancing corporate governance and shareholder returns signal a shift toward greater efficiency and market appeal. While challenges persist, including heightened US tariffs and soft domestic demand, the leadership’s “all-in” growth strategy and flexible policy framework highlight a clear long-term vision for sustainable development. For investors, China in 2025 presents a wealth of opportunities across a range of sectors—from cutting-edge technology and dividend-focused equities to stable government bonds and a recovering real estate market. In this article, our Partner & Co-CIO David Lai suggests that this year could be one of the strategic investments for China with potential for substantial returns.
Jan 06, 2025
US equities sentiment is now maximum bullish despite great policy uncertainties – altogether posing considerable risk to late-cycle momentum chasers. The US economy had barely cooled down before it was stimulated by 100 basis points in rate cuts in just three months from September 2024. The cuts started just when the US economy was rebounding. More importantly, they came after US inflation started picking up again. In fact, the US stock market is now in the grip of “Trumpian euphoria” because market expects the incoming administration will likely be supportive of even stronger growth, through more debt and deficits and extreme economic nationalism. The imminent risk now is that the US will have to pay more for its borrowings despite its dominance of the global debt market. This is not about other countries bypassing the Dollar in trade. It is about inflation – which will likely be worsened by President-elect Trump’s inflationary policies – and the term premia. In this article, our Senior Advisor Say Boon Lim discusses why US equities are in a bubble, drivers behind the Trumpian Euphoria 2.0, and that the stubborn or even revived inflation are credible risks in 2025.
Dec 23, 2024
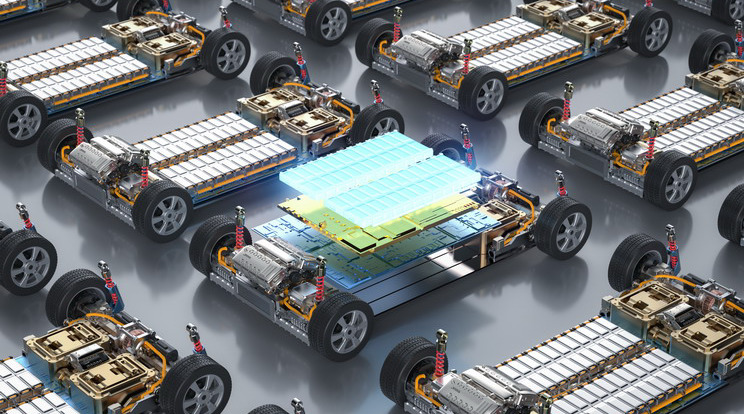
The latest developments in the battery industry continue to favour the world’s biggest players. Apart from their gains from the robust growth in EV sales, the latest developments in battery technology also work in their favour, given their significant investments in R&D spending. Over the next five years or so, lithium iron phosphate (LFP) and ternary (NCM) lithium batteries will remain the mainstream products in the mass and high-end segments respectively. These are the products that CATL and BYD lead globally. Beyond that, CATL and BYD are already moving rapidly in the area of solid-state batteries (SSBs), a potentially disruptive technology. In this article, we discuss about why the Chinese battery makers will continue to dominant the global market and benefit from their technological advancements that revolutionize the energy storage landscape.
Nov 14, 2024
The third quarter ended with a bang for mainland Chinese stocks, as twin announcements from China’s central bank and top fiscal policymakers gave both foreign and domestic investors plenty to think about over an extended market holiday during China’s October Golden Week. In this insight, Dr. Phillip Wool, Global Head of Research of Rayliant Global Advisors, explores the shift in sentiment that sent the onshore China markets higher for the quarter, breaking down the economic implications of a renewed and forceful stimulus push, the factor drivers of Q3 equity performance, and the data investors should be looking forward to as 2024 draws to a close.
Nov 14, 2024
Further to the insight piece on “Taiwan: The Quiet World-Beater” shared by our Senior Advisor Say Boon Lim, in this article we share more about our new ETF Premia FTSE TWSE Taiwan 50 ETF, which covers the 50 largest flagship companies in Taiwan by market capitalization. The strategy aims to capture the strong market performance from the robust growth in demand for semiconductors and the broader economic growth activities in Taiwan in the coming years. It is designed as a low-cost, tax efficient access tool, with versatility of having both HKD (distributing) and USD (accumulating) unit classes.
Oct 08, 2024
As the US Fed rate cut gets imminent, the liquid Asia credit market also is set to benefit from a number of strong tailwinds. In addition to favourable macroeconomic fundamentals, the heterogenous region also offers benefits of broad geographic diversification benefits and positive reinforcement from continued market liberalization and more investor friendly reforms. Within this space, Asian investment grade (IG) bonds also enter a favourable “Goldilocks” scenario in particular, represent a sweet spot that international allocators sometimes overlook, offering meaningfully higher yields, better credit ratings, and shorter duration than their peer IG cohorts from the US and Europe.
Sep 15, 2024
Given the inextricable links between energy-hungry Artificial Intelligence and renewables, energy storage and smart grids are a necessary “final mile solution” in the intensifying AI race. They provide the critical capability to store and dispatch huge quantities of uninterrupted renewable energy/power on demand without compromising emission reduction targets. In this regard, China is uniquely positioned to tackle the related challenges of AI and renewable energy with its rapid development and upgrades of energy storage systems and smart grids. In fact the country has long been studying intertwined strategic relationship between AI, technology and energy, and studiously incorporate such thinking into its Five Year Plans, and which are subsequently being rolled out as China’s East Data West Computing initiative. Further to our recent insight on China’s “power infrastructure” as the critical enabler for AI-development, in this article, we zoom in on China’s capabilities and investment opportunities in energy storage as the linchpin that holds the last mile solution, and matches renewable energy production with industrial demand in China’s journey to a high-tech, modern society.
Sep 10, 2024
In the midst of the AI-driven excitement surrounding major US tech giants, Taiwan has been quietly positioning itself as a significant player in the global technology sector. Over the past two years, Taiwan’s stock market has outperformed all major Asian markets and even surpassed the S&P 500 and Nasdaq 100 in returns. This success can largely be attributed to Taiwan's critical role in the semiconductor industry, which continues to drive its economic growth and investment appeal. In this article, our Senior Advisor Say Boon Lim discusses drivers supporting the unique, strategic moat Taiwan has built over the years, and why it will likely remain an attractive investment destination going forwards, on the expected continued robust growth in demand for semiconductors and its broader economic growth activities over coming years.
Sep 04, 2024
The time has come – Federal Reserve chair Jerome Powell finally signalled that rate cuts will likely start in Sep at Jackson Hole, though his remarks offered few clues as to how the Fed might proceed after its Sep gathering. On the surface, extending duration in US Treasuries appears to be a straightforward decision given the assumption that falling interest rates will lead to rising bond prices. However, it is not without risks and complexity as we are entering the rate cut cycle against very different backdrop from previous cycles. In this article, we discuss the intricacies of the upcoming rate cut trajectory, and why US Treasury Floating Rate Notes (FRNs) remains a relevant strategy for investors seeking diversification and stability as a result of the very much inverted yield curve, and market uncertainties in this journey.
Aug 27, 2024
Going into a July meeting of top party officials at China’s Third Plenum, held once every five years, first-quarter hopes of a 2024 recovery in China’s economy had given way to macro uncertainty, as strength in manufacturing and exports served for many to highlight just how weak domestic sentiment and consumption remain. In this article, Dr. Phillip Wool, Global Head of Research of Rayliant Global Advisors, digs into such challenges and potential paths forward for Beijing, including our thoughts on a Third Plenum meeting that didn’t yield any policy bombshells, but still offers clues as to where investors might focus as we enter the second half ready for bargain hunting.
Jul 29, 2024
Premia 圖說
吳偉鋒
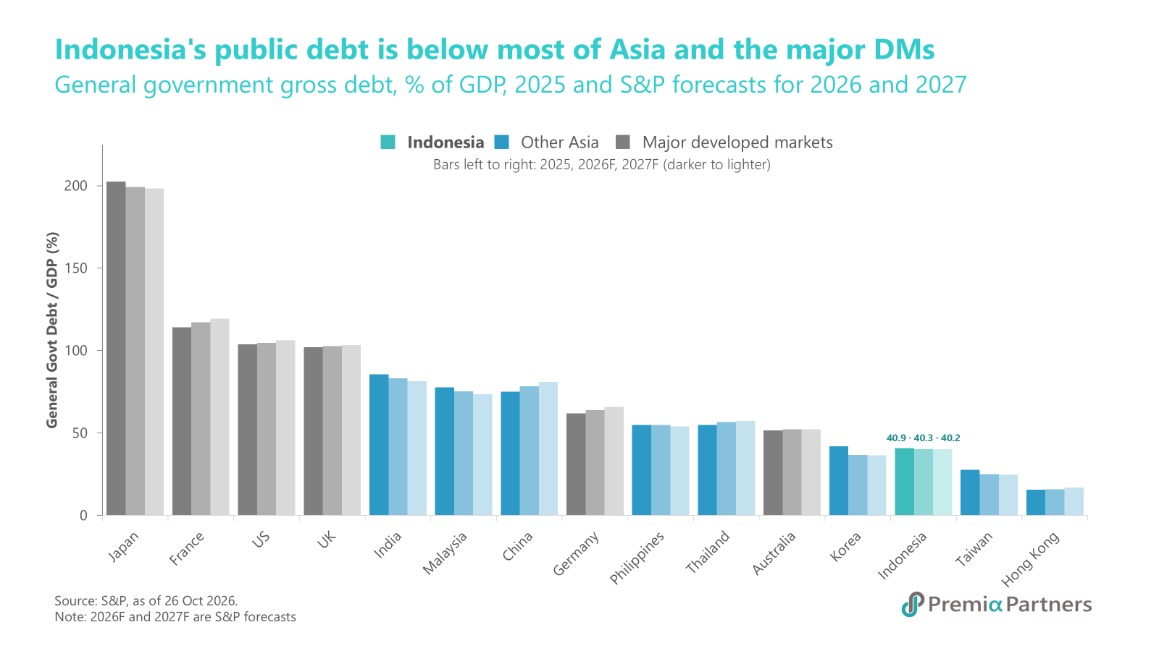
Indonesia's fiscal position is stronger than the recent sell-off implies. S&P puts general government debt at 40.9% of GDP in 2025, the third lowest of the 15 markets in the chart, and expects it to hold broadly steady at 40.3% in 2026 and 40.2% in 2027. That compares with a simple Asian average of 52.7% easing to 51.7%, and a major developed-market average of 106.0% rising to 107.6%. Japan, India, Malaysia and China all carry heavier debt loads.What rattled markets was an equity-market issue, not a fiscal one. On 15 October, MSCI proposed moving Indonesia from “Emerging Market“ to “Standalone Market“ status, citing opaque shareholding structures and suspected coordinated trading. Jakarta shares fell 11.6% in a single session, the steepest one-day drop since 1998. Indonesia government international bonds and sukuk, by contrast, barely flinched: five-year CDS widened from roughly 84–88bp in late September to around 100bp by 22 October, with part of that move predating MSCI's announcement and tracking higher US Treasury yields.Nothing has yet changed in Indonesia's index status. MSCI will consult until April 2027 and announce a final decision by 30 June 2027, leaving time for reform. Authorities have already moved, mandating a 15% minimum free float, requiring disclosure of 1% shareholdings and removing highly concentrated stocks from the JCI. Enforcement will decide the outcome, but if these measures stick, the episode could leave Indonesia with a more transparent and investable market than before.The Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF (3411 / 9411 HK) holds Indonesia as one exposure among many. The ETF spans 124 issuers across Asia ex-Japan, with Indonesia at roughly 15%: about 10% across Indonesian government bonds and sukuk, and 5% across quasi-sovereign and corporate names including Bank Mandiri, Freeport Indonesia, Indofood, Indonesia Asahan Aluminium, Minejesa Power, Pertamina and PT Perusahaan Listrik Negara - high-quality investment-grade issuers.
Oct 28, 2026