精選觀點 & Webinar
China’s A-share market is turning the corner, as investors looking past weak data and piling back into growth. Signs of rotation by domestic investors from bank deposits and safe haven assets to equity market increasingly validate investor confidence is back. Policy momentum, attractive valuations, and light foreign positioning are fueling a durable rally, echoing the 2016 supply-side reform. Leadership is shifting decisively to innovation-driven sectors — from biotech and healthcare to solar, AI, and robotics — where structural growth and global relevance are accelerating, and are expected to be important focus in China’s upcoming 15th Five Year Plan. In this article, our Partner & Co-CIO David Lai and Portfolio Manager Alex Chu discuss why, with sentiment improving and risk appetite returning, the best way to play China’s new growth cycle is through high-conviction exposure via Premia’s STAR50 ETF and CSI Caixin New Economy ETF.
Aug 26, 2025
China's STAR Market appears poised for a major growth surge, fueled by a wave of innovative robotics companies set to launch their initial public offerings. Leading industry players, including Unitree, Zhiyuan Robot, Jaka Robotics, Fine Motion Tech, and Sichuan Tianlian Robot, are all in the IPO pipeline. In this article, we will introduce these firms that are at the forefront of technological innovation in humanoid and industrial robotics, whose momentum is expected to accelerate, driven by ongoing industry innovation and the favorable policy tailwinds of China's upcoming 15th Five-Year Plan.
Aug 25, 2025
Even for the prepared and informed, at the recent World Artificial Intelligence Conference (WAIC 2025), China has still taken the world by surprise with the debutante of its fleet of over 150 AI-powered humanoid robots. Indeed 2025 marks the beginning of commercialization and production of these futuristic robots, now made reality. While humanoid robots have captured the imagination of the popular media, there has been a more important revolution in the broader robotics industry, where China has emerged, as the global powerhouse, just as it did in renewable energy and electric vehicles. In this article, we discuss how humanoid industrial robots have quickly been integrated in China’s production lines, filling the productivity void from the country’s aging population, while further driving down the manufacturing production costs with high degree of automation with these embodied AI applications.
Aug 06, 2025
Equities around the world rebounded from early-April “Liberation Day” lows, as markets increasingly reckoned the White House’s tariff bark may be worse than its bite, leading stocks in China—one of America’s biggest trading partners, and an economy viewed to be in the crosshairs of Trump 2.0 trade policy—to rise in Q2. In this article, Dr. Phillip Wool, Global Head of Research of Rayliant Global Advisors, discusses the presently muted impact of tariffs on China’s exports and explain what might be needed to ensure a sustained A-share rally.
Jul 31, 2025
Asia USD Investment Grade Credits and Saudi Government Sukuk have outperformed in a global fixed income market that has been shaken by fiscal profligacy, geopolitical tensions, tariff uncertainties, and even oil market volatility. The Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF and Premia BOCHK Saudi Arabia Government Sukuk ETF have emerged from this stress-test as effective alternatives in portfolios – delivering stable income, and uncorrelated returns, while still trading at a spread over US Treasuries with further room for spread compression. Indeed, their higher yields of 4.8%-4.9% (4.8% for the Premia Asia Credit Investment Grade USD Bond and 4.9% for the Premia Saudi Government Sukuk) are outstanding, considering their lower corporate and government leverage, and comparable or superior credit ratings versus global peers.
Jul 24, 2025
沙特阿拉伯自推出“2030願景”戰略以來,經濟轉型步伐舉世矚目,其資本市場,特別是固定收益市場,也隨之實現了跨越式發展。如今,沙特固定收益市場在政府及投資級債券領域,為投資者提供了極具吸引力的風險調整後回報。本文將深入探討,我們全新推出的Premia 中銀香港沙特伊斯蘭國債 ETF,如何在當前市場環境下,為投資者提供一個適時而獨特的選擇。同時為伊斯蘭債券投資者、固定收益及多資產配置者,帶來穩定收益、誘人利差及低關聯度回報。
Jul 03, 2025
China is undergoing a profound economic shift anchored in industrial upgrading and technological self-reliance. Amidst global macro uncertainties, the country's relentless focus on innovation across strategic sectors—ranging from semiconductors and artificial intelligence to robotics, green energy, and biotech—is building the foundation for sustained long-term growth. In this article, we discuss how these structural advances, often overlooked amid cyclical challenges, are already yielding tangible outcomes and positioning China at the forefront of the next wave of global industrial transformation. As policymakers are busy drafting the 15th Five Year Plan, and wrapping up the last stretch of the 14th Five Year Plan, it is also important to note how these innovation-led developments would continue to be at the forefront of the policy initiatives, and inform us of market opportunities ahead.
Jun 22, 2025
Amidst months of volatile global equity market performance and unprecedented trade policy uncertainty, the first quarter brought one of the most important events on China’s economic calendar: Beijing’s annual “Two Sessions” meeting, which offers a chance for officials to set economic targets and announce policy priorities for the year ahead. In this article, Dr. Phillip Wool, Global Head of Research of Rayliant Global Advisors, discusses how China policymakers are responding to Trump 2.0 tariff threats, and what it all means for A shares performance going into Q2.
May 07, 2025
The state of China’s consumer spending is better than how it has been portrayed in the media. Further, the latest developments and data suggest that the growth rate will get even better: The Chinese Government is placing more emphasis on domestic consumption as a driver of growth as global trade is disrupted by higher US tariffs. Meanwhile, the latest revenue figure from JD.com suggests a quickening of the pace of retail spending in the final quarter of 2024. The online retailer just reported 13.4% year-on-year growth in sales for the December quarter – the fastest growth rate in almost three years. This compares with its full year revenue growth rate of 6.8%, pointing to the rising growth momentum. In this article, we discuss about the consumption phenomenon in China, driving the decent growth of per-capita consumer spending in China at 5.1% YoY in real terms in 2024 (far higher than that of 1.8% in US).
Mar 20, 2025
It is worth noting that while the significant rally in BATJX – Baidu, Alibaba, Tencent, JD.com, Xiaomi – and the offshore listed tech/internet players have dominated headlines lately, the bottoming out of the overall China market since the policy shift in late September last year started onshore, with A shares experiencing a sharper rebound first and with a more slower but sustained trend, as domestic investors were more sensitive to the reset in policy tones and significant shift in government’s commitment to reviving economic growth and capital market activities. In this article, Partner & Co-CIO David Lai discusses the factors that could drive a more sustained outperformance in onshore equity market, and why it is a good entry point to rotate from offshore to onshore companies in policy supported sectors.
Mar 20, 2025
Premia 圖說
吳偉鋒
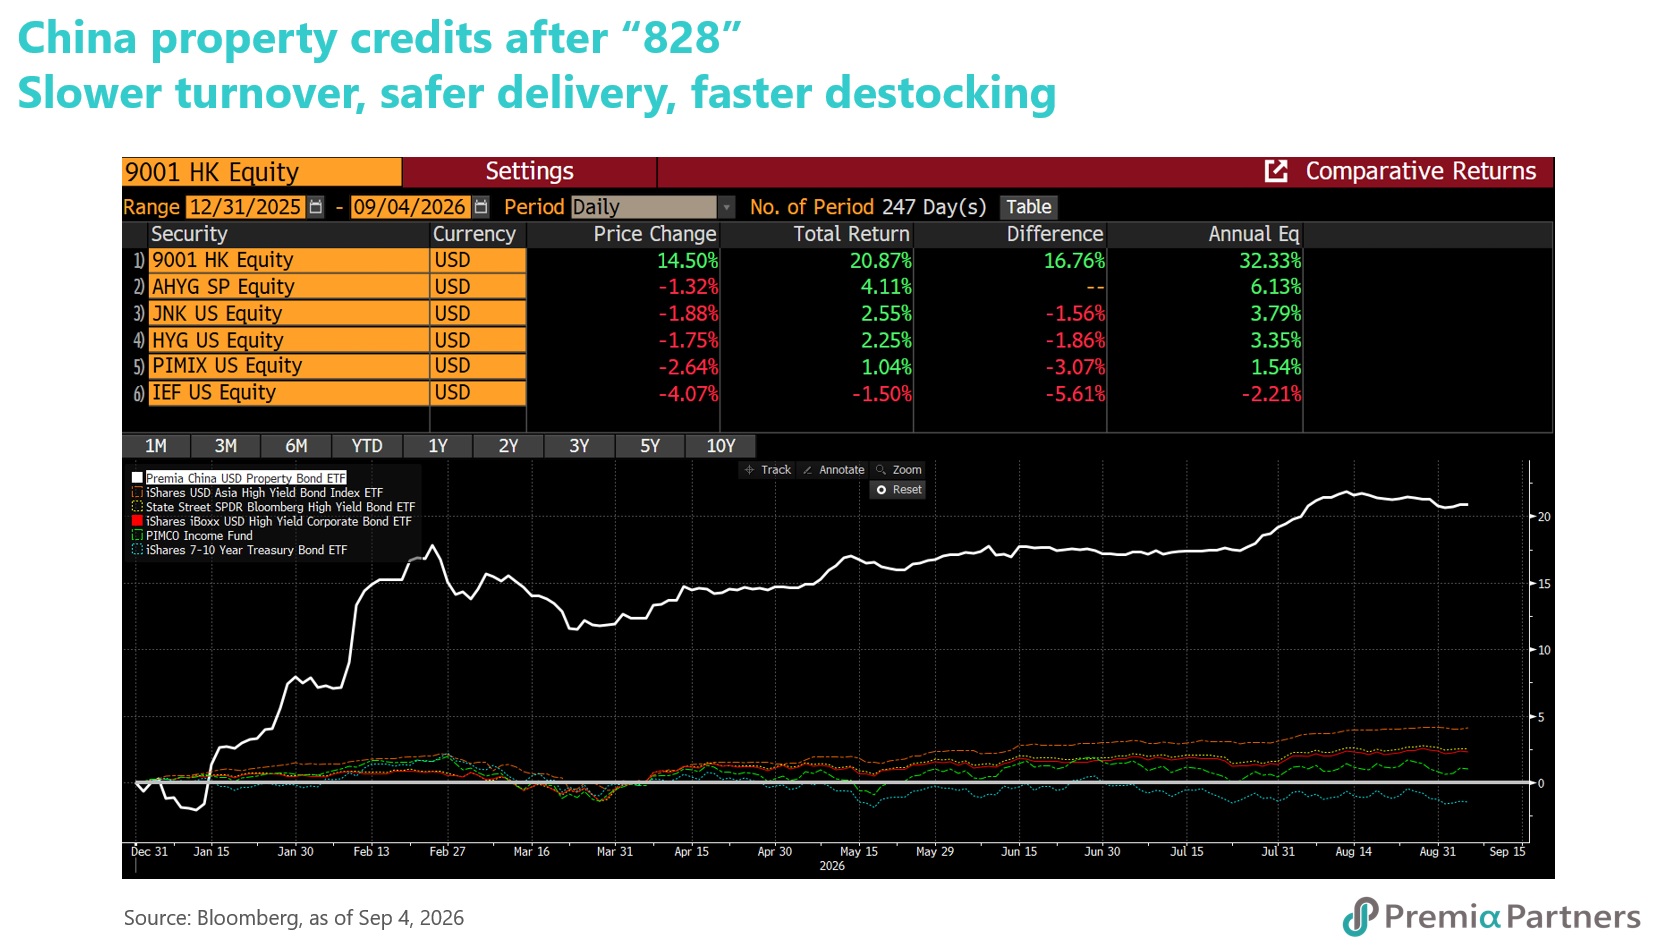
China property USD bonds have extended gains through the third quarter, with the Premia China USD Property Bond ETF (3001/9001 HK) up more than 20% year to date. On 28 August, Beijing announced the most significant overhaul of China's housing sales and financing framework in three decades. It works through four channels:Sales milestones reset. MOHURD, MNR and NFRA now require a building to be structurally topped out before presales can begin, with 100% of purchase funds — down payments and mortgage proceeds — held in supervised escrow until completion and delivery.Lead-bank oversight. Designated banks supervise project financing, escrow and construction progress end to end, and a homebuyer's mortgage is now issued only after the project is completed.Longer mortgage tenors. The PBOC lifted the maximum personal mortgage tenor from 30 to 40 years.Wider capital-market access. The CSRC broadened refinancing and M&A channels, alongside expanded REIT, CMBS and ABS support for income-producing assets.While the near-term read is negative for developers - replacing presale proceeds with borrowing implies higher leverage and more secured debt, which can subordinate existing senior claims - that argues for selection rather than avoidance. The Premia China USD Property Bond ETF (3001 / 9001 HK) holds secured and senior unsecured paper only, and excludes subordinated debt and LGFVs, favouring issuers with recurring rental income and the securitisation access the CSRC has just widened. Over the medium to long term, the reform should reduce the risk of another property-sector shock. Delivery risk moves off household prepayments and into bank-supervised project finance, lowering the odds of a repeat of the unfinished-project stress that drove the last default wave, while tighter new-home supply supports the clearing of existing inventory. Meanwhile, banks are being capitalised to carry that risk: Beijing announced a further RMB360bn (US$54bn) injection into eight state financial institutions on 6 September, of which RMB290bn (US$43.2bn) went to lenders. Brokers expect developer equities to stay soft unless policy surprises or sales data improve. Bonds answer a different question: not whether growth returns, but whether issuers keep paying. The ETF yields around 12.9% (as of Sep 8, 2026), well above the broader Asia high yield market - the extra income investors are paid for the risk that some issuers still restructure or default while the transition plays out.
Sep 10, 2026