주요 인사이트 & 웨비나
The Chinese economy continues to normalize across the board at an impressive rate, leading to the strong likelihood of it beating the current Bloomberg consensus GDP estimate growth rate of around 2% for 2020.
Oct 06, 2020
The COVID-19 pandemic could accelerate new thinking about Emerging Markets in asset allocations.
Sep 23, 2020
China economy recovered faster than the rest of the world from the pandemic as shown by various economic indicators ranging from official PMI, GDP number, steel output, excavator sales, to traffic data. China’s solid macro recovery stands out from the rest of the major economies which either remain in a lock-down mode or simply begin to resume economic activities. That explains Chinese listed companies outperformed in terms of earnings and stock price performance.
Sep 10, 2020
An overdue technical rebound in the US Dollar – which started a week ago – may give investors an opportunity to diversify their currency holdings away from the Greenback. What is emerging could well turn out to be a counter-trend rally in a bigger, multi-year Dollar decline.
Sep 09, 2020
CSI 300 outperforms S&P 500, Chinese tech outruns Nasdaq 100. How has China’s new economy sectors including its recently launched “Nasdaq” – the STAR board (Shanghai Stock Exchange’s Science and Technology Innovation Board) – outperformed global indices despite being at the center of a trade-tech war with the United States?
Sep 01, 2020
Highest recorded yield spread between the China 10Y Government Bond and the 10Y UST. The yield spread between the China 10-year government bond over the 10-year US Treasury recently hit its widest ever recorded level.
Aug 25, 2020
In the midst of a US tech bubble, Chinese and Hong Kong equities have emerged in the sweet spot between valuations, profitability and balance sheet strength.
Aug 18, 2020
Are US indices rallying because of COVID-19? The most common narrative is that “US stocks have been rising despite the pandemic.” Perhaps a more accurate explanation is “US stocks have been rising because of the pandemic”.
Aug 12, 2020
After the fall in Q1, global equities recovered sharply in Q2 as the COVID fear eases and stimulus packages kick in around the world. YTD, China is the best performing emerging market, and the broad CSI 300 index gained 14% in the second quarter. From factor investing perspective, we continue to see the dispersion of a two-speed-economy despite an overall beta pick up. Quality growth new economy stocks continue to be the winner.
Aug 11, 2020
Back to the future. Clues to US policy makers’ long game for the Dollar can be found in the long-term historical relationship between money supply growth, the inflation rate, and nominal GDP growth. Conclusion upfront: We are likely to see a long cycle of aggressive US monetary expansion ahead – to depreciate the Dollar, revive inflation, and boost nominal GDP growth.
Aug 03, 2020
토픽별
주간 차트
Michael Ng
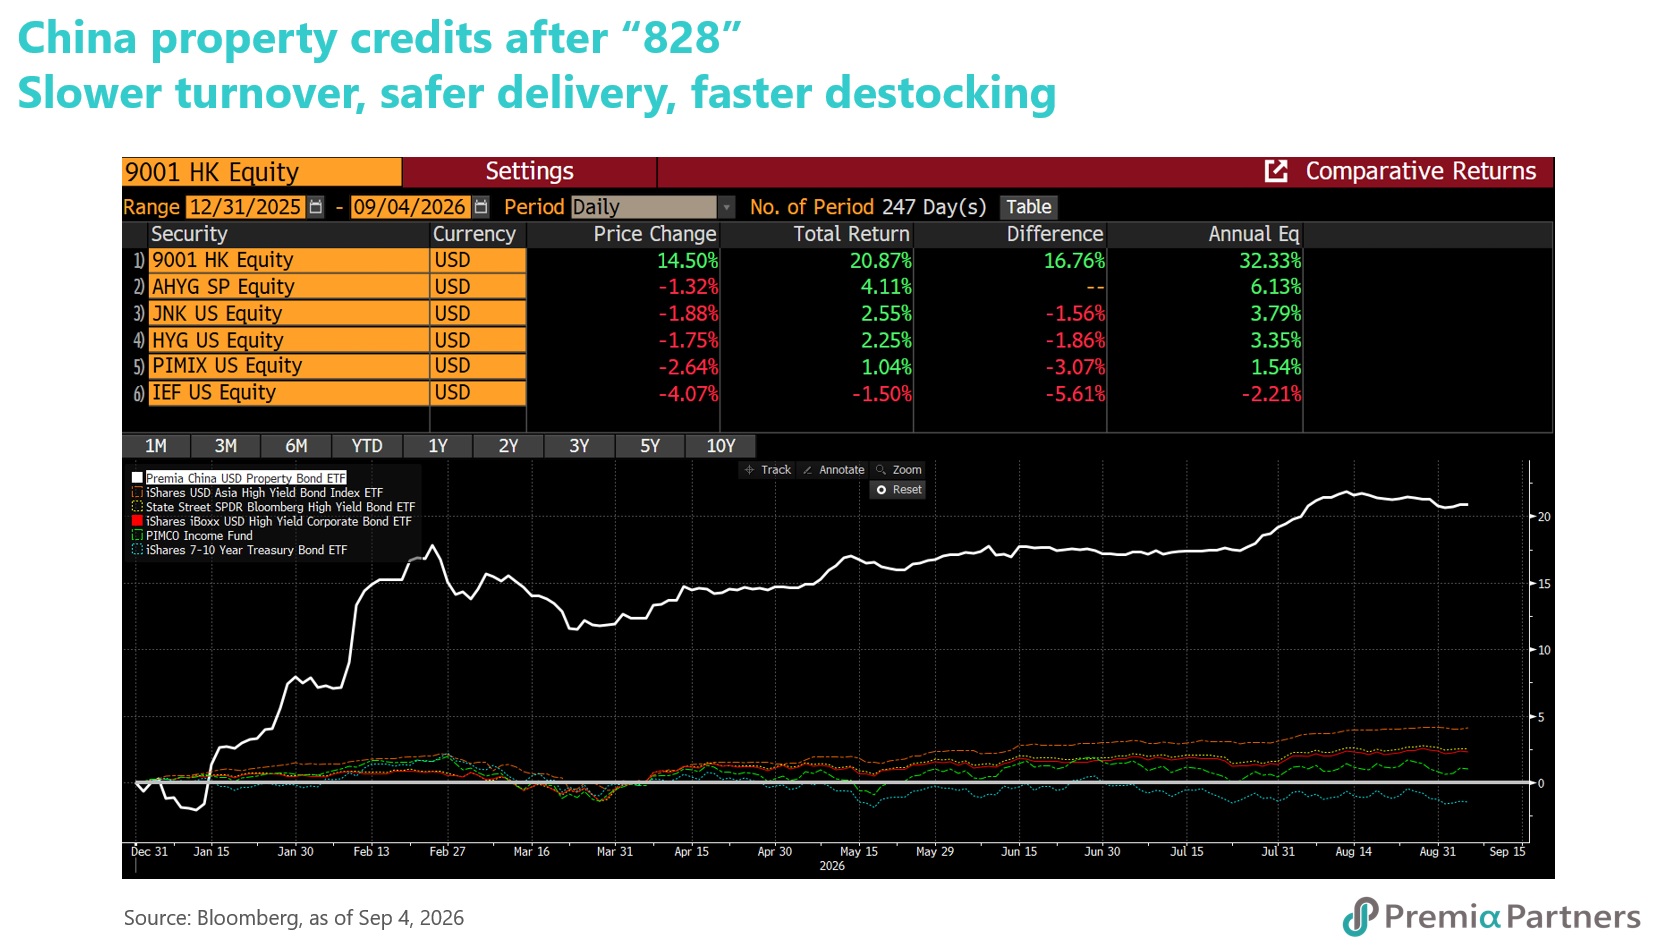
China property USD bonds have extended gains through the third quarter, with the Premia China USD Property Bond ETF (3001/9001 HK) up more than 20% year to date. On 28 August, Beijing announced the most significant overhaul of China's housing sales and financing framework in three decades. It works through four channels:Sales milestones reset. MOHURD, MNR and NFRA now require a building to be structurally topped out before presales can begin, with 100% of purchase funds — down payments and mortgage proceeds — held in supervised escrow until completion and delivery.Lead-bank oversight. Designated banks supervise project financing, escrow and construction progress end to end, and a homebuyer's mortgage is now issued only after the project is completed.Longer mortgage tenors. The PBOC lifted the maximum personal mortgage tenor from 30 to 40 years.Wider capital-market access. The CSRC broadened refinancing and M&A channels, alongside expanded REIT, CMBS and ABS support for income-producing assets.While the near-term read is negative for developers - replacing presale proceeds with borrowing implies higher leverage and more secured debt, which can subordinate existing senior claims - that argues for selection rather than avoidance. The Premia China USD Property Bond ETF (3001 / 9001 HK) holds secured and senior unsecured paper only, and excludes subordinated debt and LGFVs, favouring issuers with recurring rental income and the securitisation access the CSRC has just widened. Over the medium to long term, the reform should reduce the risk of another property-sector shock. Delivery risk moves off household prepayments and into bank-supervised project finance, lowering the odds of a repeat of the unfinished-project stress that drove the last default wave, while tighter new-home supply supports the clearing of existing inventory. Meanwhile, banks are being capitalised to carry that risk: Beijing announced a further RMB360bn (US$54bn) injection into eight state financial institutions on 6 September, of which RMB290bn (US$43.2bn) went to lenders. Brokers expect developer equities to stay soft unless policy surprises or sales data improve. Bonds answer a different question: not whether growth returns, but whether issuers keep paying. The ETF yields around 12.9% (as of Sep 8, 2026), well above the broader Asia high yield market - the extra income investors are paid for the risk that some issuers still restructure or default while the transition plays out.
Sep 10, 2026