주요 인사이트 & 웨비나
A major global trading and geopolitical event happened last week, attracting relatively little commentary from a media more preoccupied with US politics and the pandemic.
Nov 24, 2020
As business activities in China mostly resume to a normal level, we also observed some mean-reversion in factor returns, and interesting rotation in sector returns. Still, China A shares continue to outperform the US and global equity markets. With “high-quality” growth emphasized by the 14th Five-Year Plan and “Dual Circulation”, we believe “Quality Growth” will continue to be the main tone of China A equities.
Nov 11, 2020
So, it is official: Exit Donald Trump, enter President Joe Biden. And when the cheering and crying is done, we are likely to see that the election meant more emotionally to Americans than it does economically for the nation, or financially for the markets. The big economic and market trends are unlikely to be changed by the election.
Nov 09, 2020
China’s 14th, Five-Year Plan is a refreshing reiteration of conventional supply side policies, at a time when Developed Markets are in the grip of very unorthodox economic policies.
Nov 04, 2020
The term "dual circulation” is one of the hot searches in China and receives great attention after President Xi first expressed this idea at a top official meeting held earlier this year. He then elaborated further that China’s economic model will be involving an internal circulation developing a substantial domestic market, and an external circulation deepening the international trade. The latest meeting of Communist Party’s Central Committee reinforced this policy will be the core component of the 14th five-year plan for the development between 2021 and 2025.
Nov 04, 2020
The latest economic data confirms the upward trajectory of Chinese growth, putting China on track to be the only major economy to register growth for the full year 2020. And it highlights the attractiveness of China’s asset markets and supports the case for continued outperformance against other major markets.
Oct 28, 2020
Two separate news items last week focused our attention on the gap in understanding about the rapidly changing energy landscape in China.
Oct 20, 2020
Yield curve steepening – which has been accelerating in recent weeks as the market contemplates a whopper of a stimulus package under a possible Biden White House – is likely to continue regardless of the winner on November 3.
Oct 14, 2020
Since COVID we have observed that many constituents in our Premia ETFs have been silver lining beneficiaries and continue rallying notwithstanding the market volatilities, unfolding COVID situation and US China tension. Here we share the conversation with our Co-CIO David Lai and team, on some frequent topics that come up often in our client conversations, especially around China new economy ETF (3173/ 9173 HK), which registered strong YTD return* of ~40% and have become the 4th largest A shares ETF in Hong Kong as consistent inflows since April tripled its AUM to ~US$285 million.Please click here for transcript to the disscussion.*as of October 12th 2020
Oct 14, 2020
토픽별
주간 차트
Michael Ng
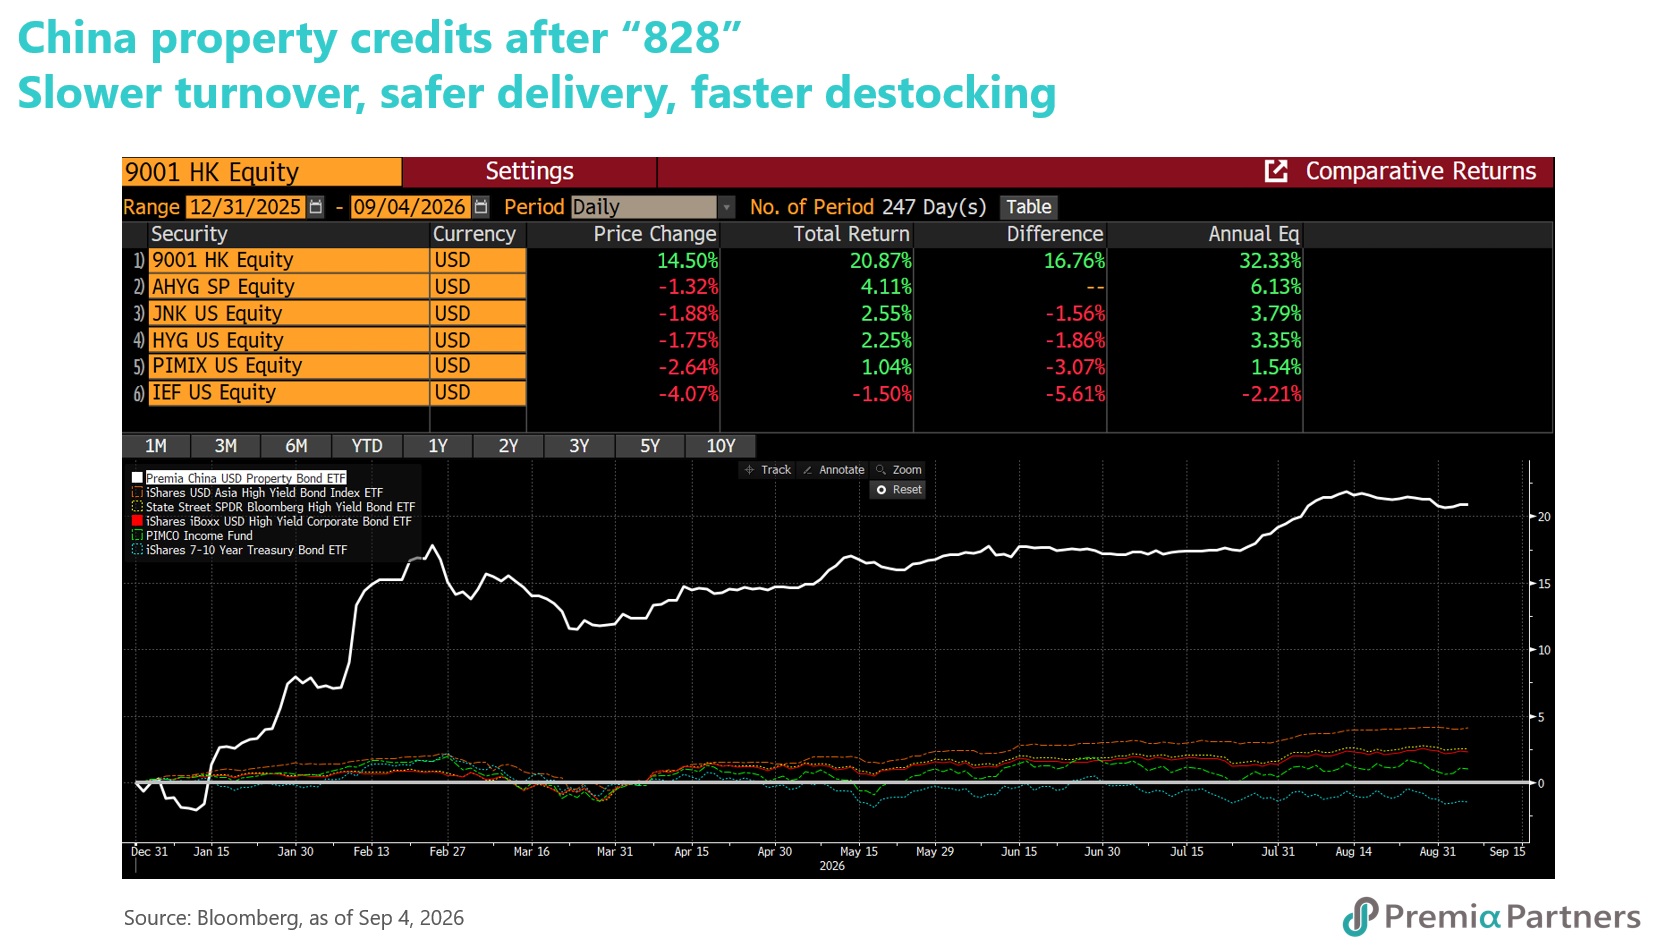
China property USD bonds have extended gains through the third quarter, with the Premia China USD Property Bond ETF (3001/9001 HK) up more than 20% year to date. On 28 August, Beijing announced the most significant overhaul of China's housing sales and financing framework in three decades. It works through four channels:Sales milestones reset. MOHURD, MNR and NFRA now require a building to be structurally topped out before presales can begin, with 100% of purchase funds — down payments and mortgage proceeds — held in supervised escrow until completion and delivery.Lead-bank oversight. Designated banks supervise project financing, escrow and construction progress end to end, and a homebuyer's mortgage is now issued only after the project is completed.Longer mortgage tenors. The PBOC lifted the maximum personal mortgage tenor from 30 to 40 years.Wider capital-market access. The CSRC broadened refinancing and M&A channels, alongside expanded REIT, CMBS and ABS support for income-producing assets.While the near-term read is negative for developers - replacing presale proceeds with borrowing implies higher leverage and more secured debt, which can subordinate existing senior claims - that argues for selection rather than avoidance. The Premia China USD Property Bond ETF (3001 / 9001 HK) holds secured and senior unsecured paper only, and excludes subordinated debt and LGFVs, favouring issuers with recurring rental income and the securitisation access the CSRC has just widened. Over the medium to long term, the reform should reduce the risk of another property-sector shock. Delivery risk moves off household prepayments and into bank-supervised project finance, lowering the odds of a repeat of the unfinished-project stress that drove the last default wave, while tighter new-home supply supports the clearing of existing inventory. Meanwhile, banks are being capitalised to carry that risk: Beijing announced a further RMB360bn (US$54bn) injection into eight state financial institutions on 6 September, of which RMB290bn (US$43.2bn) went to lenders. Brokers expect developer equities to stay soft unless policy surprises or sales data improve. Bonds answer a different question: not whether growth returns, but whether issuers keep paying. The ETF yields around 12.9% (as of Sep 8, 2026), well above the broader Asia high yield market - the extra income investors are paid for the risk that some issuers still restructure or default while the transition plays out.
Sep 10, 2026