프리미아 인사이트
주요 인사이트 & 웨비나
China market has taken a pause after a strong rally in the past few months. The renewed hawkish tone from the US Fed may be the main reason behind the consolidation. Some critics are suggesting that the China reopening trade is done, or has become overcrowded already with not much immediate upside as a tactical trade. In this article, our Partner & Co-CIO David Lai addresses this topic from various aspects ranging from macro economies, investors’ positioning, to policy agenda and market valuation. He would also share why we believe it’s onshore A-shares that are picking up the baton for the second act of the rally - as the China reopening play evolves from short term tactical, to fundamental strategic opportunities driven by positive earnings growth and restoration of business and consumer confidence.
Mar 01, 2023
Chinese stocks took a rollercoaster ride in Q4, as the immediate lacklustre reaction to October’s National Congress gave way to a rally on the back of policy support in November. Investors finally cheered Beijing’s abrupt dismantling of its restrictive zero-COVID policies, as the year came to a close. By the end of December, the CSI 300 Index was up 2% on the quarter. Below in this article, Dr. Philip Wool, Managing Director and Head of Investment Solutions of Rayliant Global Advisors, would explore critical developments in the macro picture at the turn of the year, discuss fourth-quarter performance and factor rotation pattern through the period, and also provide our thoughts as to what reopening has in store for Chinese stocks in 2023.
Feb 03, 2023
In 2022, our Premia CSI Caixin China Bedrock Economy ETF (“the Bedrock ETF”) outperformed most of the market benchmarks, such as FTSE A50, CSI 300, CSI 500 and ChiNext, by around 10-24% points. In a backdrop of weak equity performance, investors favored low beta and volatility stocks with significant economic value and good financial health, which coincided with the Bedrock ETF’s underlying index methodology and broadly explained why the ETF outperformed in 2022. In this article, we would have a more in-depth look at the portfolio holdings’ companies and decipher drivers of the outperformance and whether this multi-factor approach of low volatility, value, quality and size tilts would continue to power outperformance in 2023.
Feb 02, 2023
Big, long-term trends could drive Developed Market bond yields much higher than the cyclical peaks that the market is currently pricing in. There are cycles and there are secular trends. If the super cycle of rates and yields has turned – off deep negative inflation-adjusted levels – then the lesser cycles could mean- revert a lot higher around long-term uptrends. And we are at this juncture at the moment, as the negative yielding bonds have literally disappeared - the global stock of negative yielding bonds had gone from a peak of US$18.4 trillion late in 2020 to zero recently. What are the true implications behind this abrupt turn of tides? In this article, our Senior Advisor Say Boon Lim discusses the big drivers for potentially much higher rates and yields for this year, and areas we are spending a lot more time monitoring, as the longer-term outlook could be far worse than just a mean reversion in nominal rates and yields as we may also be in the midst of a secular mean reversion in real government bond yields and corporate credit yields.
Jan 16, 2023

2023년, 투자자들은 경제침체기를 맞게될 서양과 중국의 회복으로 가파른 성장세에 올라탈 동양 사이에 극명한 경제적 차이를 보게 될 것입니다. 2022년, 재개방 반등세를 이미 자체적으로 경험한 ASEAN-5국가들이 내년에는 중국의 재개방 회복세 순풍에 올라탈 것으로 전망됩니다. 이번 논설에서는 ASEAN-5 국가들이2023년 비교적 완만한 인플레와 세계적으로도 가장 높은 수준의 경제성장률을 시현하며 어떻게 스윗스폿(Sweet Spot)을 계속 선점하게 될 지 다뤄볼 예정입니다.
Dec 12, 2022
2023년, 투자자들은 경제침체를 맞게 될 서양과 중국시장 회복 영향으로 가파른 성장세를 보일 동양 사이에 극명한 경제 차이를 보게 될 것입니다. 내년 중국 재개방 회복세는2022년 재개방 반등세를 이미 자체적으로 경험한 ASEAN-5국가들에 또 한번의 뒷바람으로 작용할 것으로 전망됩니다. 이번 논설에서는 ASEAN-5 국가들이2023년 비교적 완만한 인플레와 세계적으로도 가장 높은 수준의 경제성장률을 시현하며 어떻게 최적 지점(Sweet Spot)을 계속 선점할 수 있을지 다뤄볼 예정입니다.
Dec 11, 2022
G20 정상회담 이후 개선된 시장심리와 최근 중국의 제로 코로나 정책 완화에 대한 기대감으로 기술주를 포함한 성장주들이 상승궤도에 본격 진입하여 수차례의 상승스윙과 랠리를 보기 시작했다. 타 미국 기술주들과는 달리 일찍이 조정기에 대거 진입했던 아시아 혁신기술 메타버스 리딩 기업들은 조정사이클에서 그만큼 먼저 벗어나 다수의 요인으로 발생된 순풍을 타고 상승세에 다시 접어든 것으로 보인다. 투자자들이 메타버스와 혁신기술 분야에 대한 투자기회를 다시 엿보기 시작하는 와중에 우리는 아시아의 기회들을 어떤 방식으로 구성하여 미국 편향적인 글로벌 테크전략들이 일반적으로 놓치는 부분을 메울 수 있을까? 이 영상에서는 디지털 전환, 로봇 & 자동화, 혁신 녹색기술 방면의 기회 뿐만 아니라 기업과 소비자 공간에 큰 변화를 가져다 준 메타버스 관련(가상 인플루언서 포함) 기회들까지 모두 담을 수 있게 설계된 Premia Asia Innovative Technology & Metaverse Theme ETF (3181/ 9181 HK) 의 구성에 대해 정리해보았다.2018년에 처음 선보인 해당 ETF는 섹터와 지역별 분산투자 혜택으로 글로벌, 미국, 중국 시장에 편중된 유사 상품들의 2개년, 3개년, 5개년 수익률을 능가하고 있다. 2019년, 2020년 강한 상승장 속 40%, 60%의 수익률을 시현했을 뿐 아니라, 2021년에는 -7%대의 수익률을 유지하며 상승장과 하락장에서 모두 아웃퍼폼하는 성과를 보여주었다. 해당 ETF는 아시아 테크 업종 내 전략적 성장 기회를 노리고 있는 투자자들에게 필요한 효과적이고 균형잡힌 투자 도구가 될 것이다.
Dec 08, 2022
2022년에는 전세계적으로 투자자들이 플러스 수익률을 낼 수 있는 시장을 찾는 것 자체가 어려웠습니다. 중국시장 역시 H주, A주, ADR주 모두 올해 첫 11개월 간 달러 수익률이 20~29%씩 하락하는 등 매도세에서 벗어날 수 없었는데요. 외국인 투자자들의 순매도세가 이어지는 동안 시장 회전율은 감소하였습니다. 중국 내부적으로 잦은 코로나 봉쇄조치, 부동산 시장 침체, 계속되는 빅테크 감시, 미중 관계 악화 등의 요인 모두 중국 증시 약세 기조에 기여했습니다. 대외적으로는 우크라이나-러시아 전쟁, 높은 인플레 압력, 가속화된 금리 인상 주기, 달러 강세 등의 이벤트들로 인해 위험자산에 대한 투자자 신뢰도가 더욱 약화되었습니다.
Dec 05, 2022
In a discordant world, there are no overarching investment themes. The different parts of the world are marching to different drums – their economies and markets are driven by different cycles, different prior policy choices and factors beyond their control. The US economy and market are paying back for the extreme policy stimulus of 2020-2021. Europeans are paying back for the same, with the added pain of a war outside their control. Japan is battling a chronic ailment – extreme debt – made acute by sharply higher cost of US funds. China is at the bottom of its policy cycle, at the beginning of a path out of COVID health controls.
Dec 04, 2022
After finishing Q2 as the only emerging market in positive territory, the effects of zero-COVID policy, a continued slump in the property market, and weakening global demand pushed Chinese stocks to the bottom of the EM index in Q3. The CSI 300 Index dropped by -14.3% over the three months from July to September 2022. Below, we offer deeper insights into third-quarter performance—including some bright spots among state-owned enterprises and technology with a policy tailwind—along with our thinking on October’s National Congress and what the rest of the year might have in store.
Oct 30, 2022
토픽별
주간 차트
Michael Ng
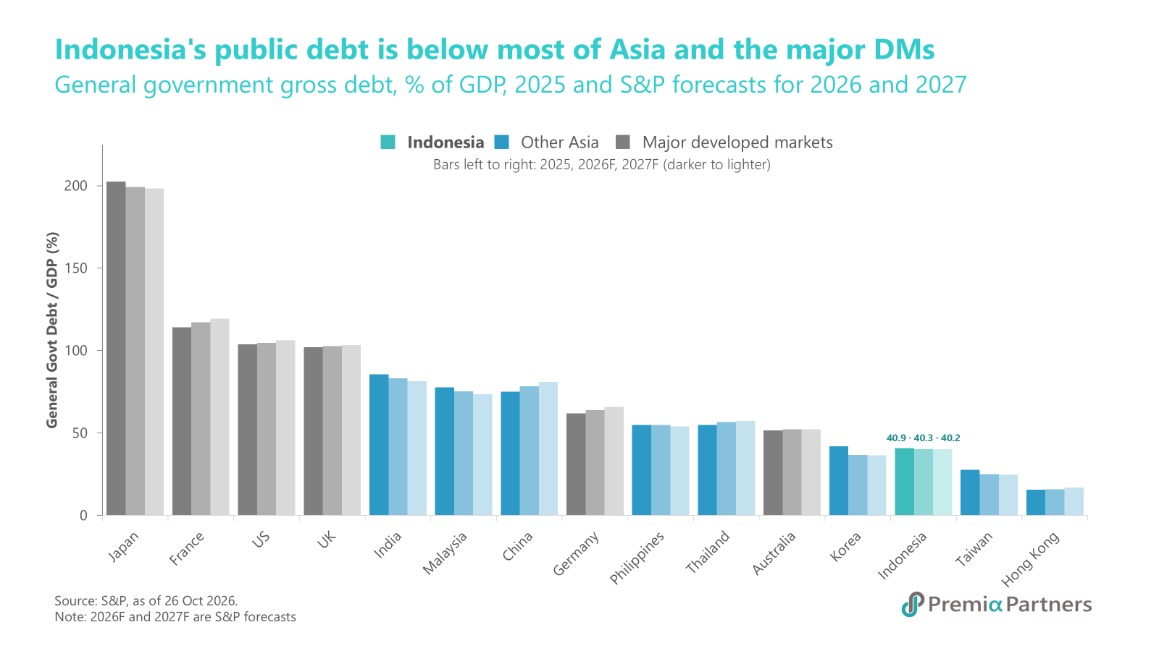
Indonesia's fiscal position is stronger than the recent sell-off implies. S&P puts general government debt at 40.9% of GDP in 2025, the third lowest of the 15 markets in the chart, and expects it to hold broadly steady at 40.3% in 2026 and 40.2% in 2027. That compares with a simple Asian average of 52.7% easing to 51.7%, and a major developed-market average of 106.0% rising to 107.6%. Japan, India, Malaysia and China all carry heavier debt loads.What rattled markets was an equity-market issue, not a fiscal one. On 15 October, MSCI proposed moving Indonesia from “Emerging Market“ to “Standalone Market“ status, citing opaque shareholding structures and suspected coordinated trading. Jakarta shares fell 11.6% in a single session, the steepest one-day drop since 1998. Indonesia government international bonds and sukuk, by contrast, barely flinched: five-year CDS widened from roughly 84–88bp in late September to around 100bp by 22 October, with part of that move predating MSCI's announcement and tracking higher US Treasury yields.Nothing has yet changed in Indonesia's index status. MSCI will consult until April 2027 and announce a final decision by 30 June 2027, leaving time for reform. Authorities have already moved, mandating a 15% minimum free float, requiring disclosure of 1% shareholdings and removing highly concentrated stocks from the JCI. Enforcement will decide the outcome, but if these measures stick, the episode could leave Indonesia with a more transparent and investable market than before.The Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF (3411 / 9411 HK) holds Indonesia as one exposure among many. The ETF spans 124 issuers across Asia ex-Japan, with Indonesia at roughly 15%: about 10% across Indonesian government bonds and sukuk, and 5% across quasi-sovereign and corporate names including Bank Mandiri, Freeport Indonesia, Indofood, Indonesia Asahan Aluminium, Minejesa Power, Pertamina and PT Perusahaan Listrik Negara - high-quality investment-grade issuers.
Oct 28, 2026