Premia 觀點洞察
精選觀點 & Webinar
The COVID-19 outbreak has led to a worldwide pandemic, a global slowdown, arguably a recession and hopefully not a depression. Business activities globally have been halted due to the outbreak and demand has been shrinking significantly as well. Apart from some of the Asian countries including China, we have yet seen an inflection point of the case curves in most countries. In this article, we’d like to share some notable leading Chinese players in the space that have been working hard to fight against the virus for the domestic and global community.
Apr 02, 2020
The virous outbreak becomes one of the largest threats to the global economy and financial markets in decades. Will China, the one which has been suffered from the pandemic first, be able to bounce back first and lead the recovery worldwide like the Global Financial Crisis back in 2008? The latest call in new infrastructure investment maybe the key.
Mar 19, 2020
COVID-19 spread accelerating in the US, even as the number of new infections in China eases Impact will be significant on the largely consumer-driven US economy Markets are either in or on the brink of bear territory, and this is an angry bear Recession likely already in progress in Japan; possible recession in Europe; near zero GDP growth likely in the US by 2Q20 Corporate credit protection costs have started rising – more trouble ahead Seek safety in cash and US Treasury-related instruments
Mar 09, 2020
The coronavirus situation in China seems to have improved a lot, and now many are worried about what will happen as the factories get back on their feet. How's the progress so far?
Mar 09, 2020
客戶時常和我們反映,他們非常喜歡Premia旗下的亞洲策略,不過由於ETF的流動性不高,因此僅能尋求一些美國或歐洲上市的類似的ETF。不過,其實投資者真正在意的並不是流動性本身,而是流動性成本。流動性和成本息息相關——流動性愈低,交易進出的成本就愈高,特別是在金融危機或市場失衡時期,其流動性可能跌至零。目前仍有許多投資者選擇在美國或歐洲交易亞洲資產,認為這樣的交易方式較為高效且便宜,不過這可能並不是一個明智的選擇。在這次的網路研討會中,我們將與您分享對於評估ETF流動性的觀點,並分別以在紐約、倫敦和香港上市的ETF,比較投資越南市場的優劣。
Mar 09, 2020
Relief rally unlikely to last Beyond COVID-19, economies could flatline or enter recession Corporate earnings could stop growing at a time of heightened valuations There is a tail risk of credit defaults on liquidity and cashflow squeeze
Mar 02, 2020
As we expected, markets did bounce on policy stimulus hopes. While rate cuts and liquidity injections will make markets feel better for a while at least, what is it likely to do for the economy?
Mar 02, 2020
在疫情爆發的艱難時刻下,我們看到了一個不同的社會運作生態。即使隔離在家,我們看到數億人在通過網絡購物、遠程辦公、雲直播學習,人們的日常生活行為在被動或主動地轉變到一個不可思議的“新常態”。在本期網絡直播中,我們將分享科技所賦予的結構性大趨勢、所創造的更聯結包容的社會形態、以及投資者可以如何通過我們的亞洲創新科技策略捕捉這些驅動亞洲乃至全球可持續生產力的創新領導企業。
Mar 02, 2020
The sharp pullback in developed markets could see 10% knocked off the S&P 500 The correction was due to a more complex mix of factors than just COVID-19 A rebound could emerge on monetary stimulus hopes But deeper problems of overvaluation and negligible earnings growth will remain to trouble markets later in the year
Feb 24, 2020
Recent market rallies, despite COVID-19, are neither “ill informed” nor “complacent” Markets are looking past the viral outbreak Stocks will likely return to being driven by whatever the trends were before the outbreak Developed markets are at the tail end of bull moves – they could edge a bit higher but the risks are on the downside, and that's got nothing to do with COVID-19 either Chinese equities could ironically outperform developed market stocks this year
Feb 23, 2020
Premia 圖說
吳偉鋒
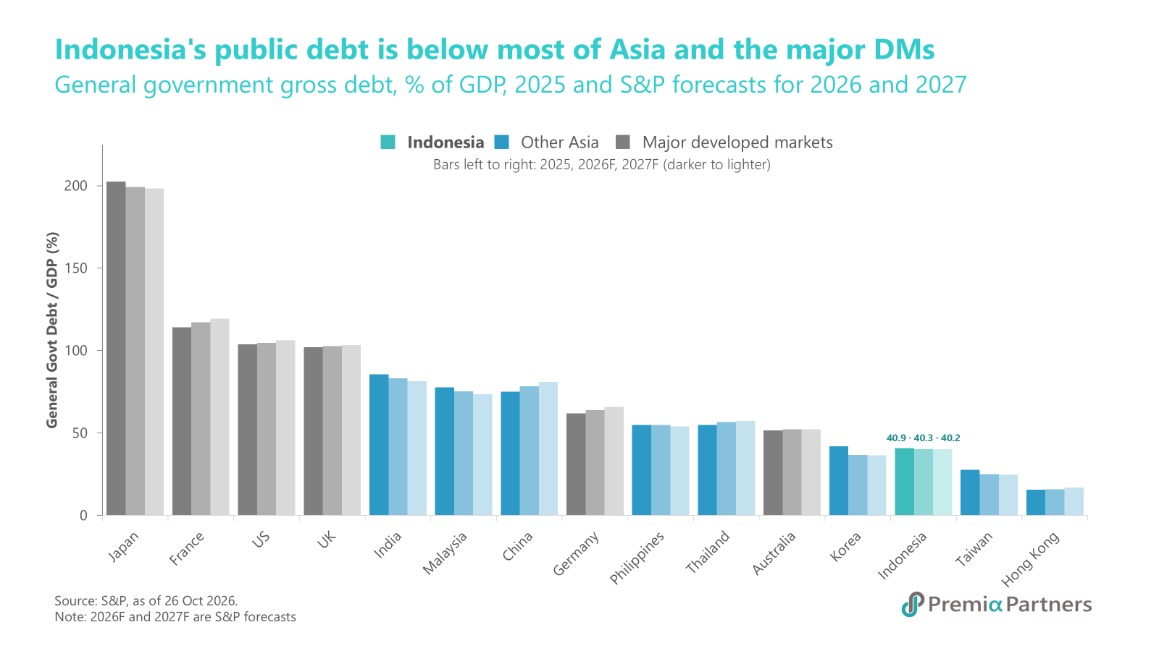
Indonesia's fiscal position is stronger than the recent sell-off implies. S&P puts general government debt at 40.9% of GDP in 2025, the third lowest of the 15 markets in the chart, and expects it to hold broadly steady at 40.3% in 2026 and 40.2% in 2027. That compares with a simple Asian average of 52.7% easing to 51.7%, and a major developed-market average of 106.0% rising to 107.6%. Japan, India, Malaysia and China all carry heavier debt loads.What rattled markets was an equity-market issue, not a fiscal one. On 15 October, MSCI proposed moving Indonesia from “Emerging Market“ to “Standalone Market“ status, citing opaque shareholding structures and suspected coordinated trading. Jakarta shares fell 11.6% in a single session, the steepest one-day drop since 1998. Indonesia government international bonds and sukuk, by contrast, barely flinched: five-year CDS widened from roughly 84–88bp in late September to around 100bp by 22 October, with part of that move predating MSCI's announcement and tracking higher US Treasury yields.Nothing has yet changed in Indonesia's index status. MSCI will consult until April 2027 and announce a final decision by 30 June 2027, leaving time for reform. Authorities have already moved, mandating a 15% minimum free float, requiring disclosure of 1% shareholdings and removing highly concentrated stocks from the JCI. Enforcement will decide the outcome, but if these measures stick, the episode could leave Indonesia with a more transparent and investable market than before.The Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF (3411 / 9411 HK) holds Indonesia as one exposure among many. The ETF spans 124 issuers across Asia ex-Japan, with Indonesia at roughly 15%: about 10% across Indonesian government bonds and sukuk, and 5% across quasi-sovereign and corporate names including Bank Mandiri, Freeport Indonesia, Indofood, Indonesia Asahan Aluminium, Minejesa Power, Pertamina and PT Perusahaan Listrik Negara - high-quality investment-grade issuers.
Oct 28, 2026